Rules
Seller financing in a business sale: what the promissory note should include
Seller financing terms in a business sale: what the promissory note has to state, who files the UCC-1 and what a lapsed lien costs the seller.
What to take away
- A seller note is a contract first and a security device second. A court reads the rate, the payment schedule, the maturity date and the default clause literally.
- State usury law sets the ceiling on what a seller may charge. Federal lending disclosure rules do not reach a note from a business buyer.
- Collateral turns on paperworkan authenticated security agreement and a UCC-1 filed where the buyer is organized.
- A lapsed or unperfected filing drops the seller behind the bank, behind judgment creditors and behind a bankruptcy trustee.
Who sets the rules for a seller note
Congress does not set the interest ceiling on the sale of a small business. That belongs to the states through their usury statutes, and to the Uniform Commercial Code as each state has adopted it.
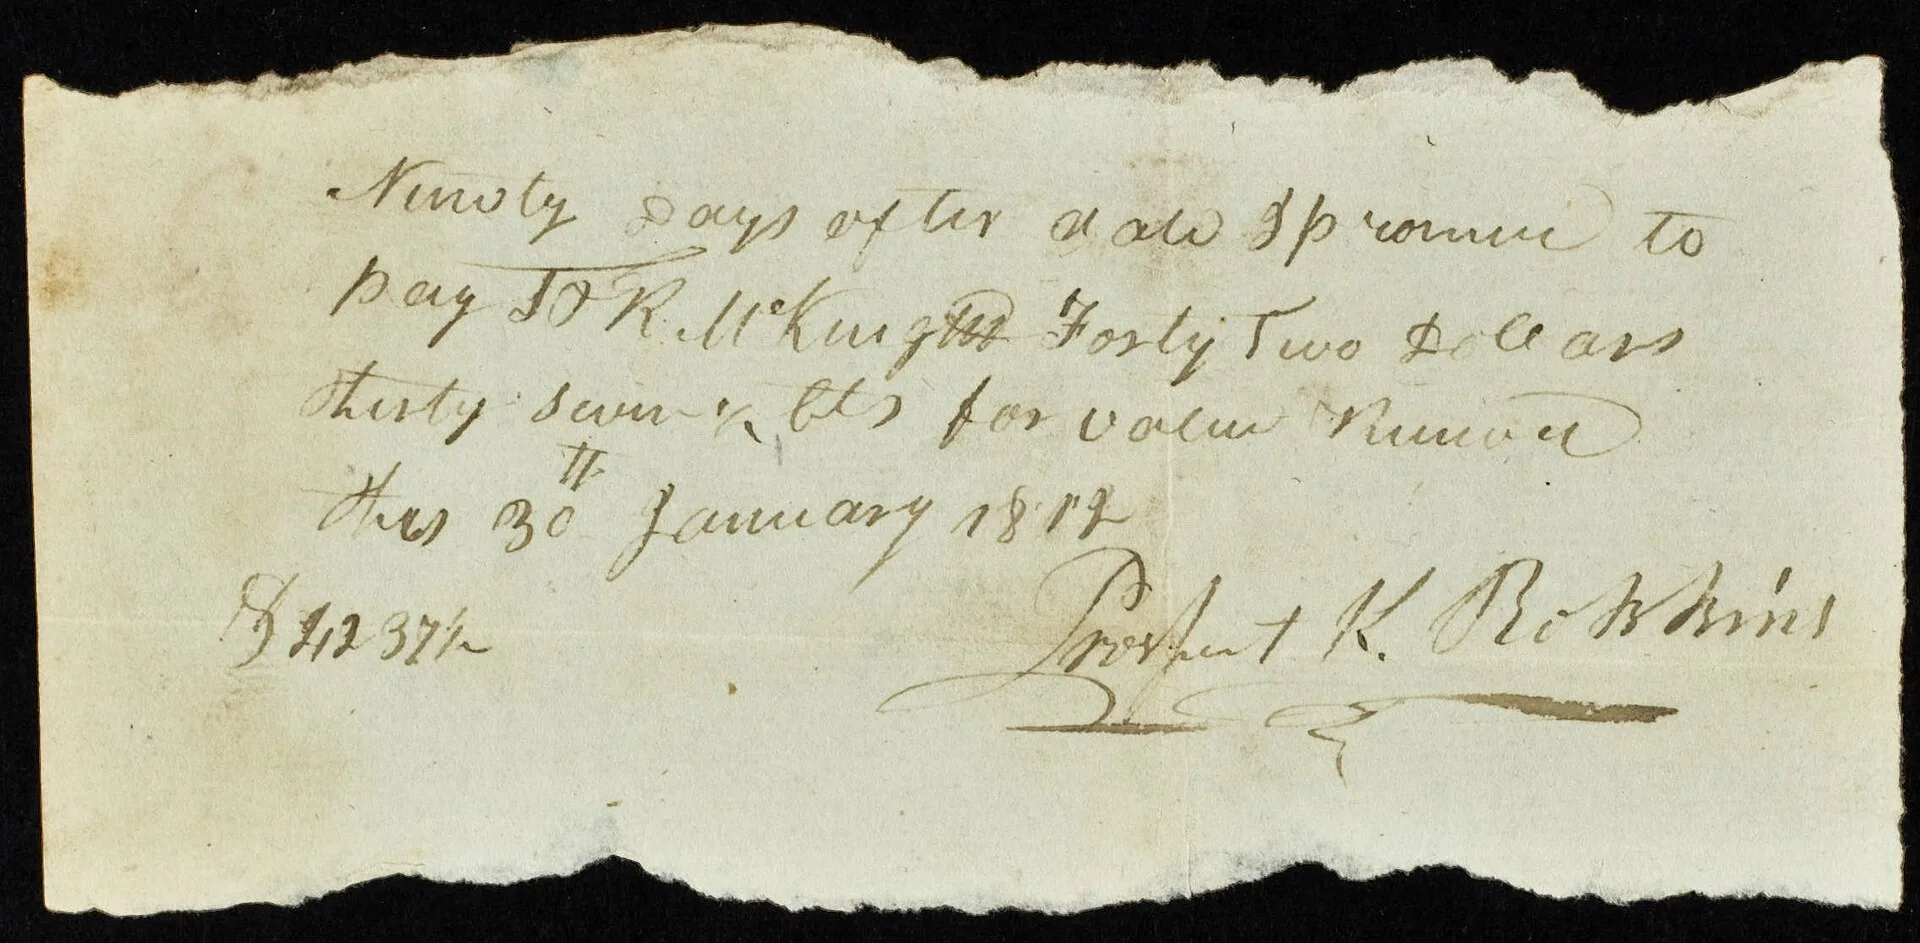
The federal Truth in Lending Act and Regulation Z cover consumer credit. A note given by a business buyer for a business purpose sits outside them, so no federal disclosure statement is required. Cornell Law School's page on the promissory note lists what courts expect: a written promise, a definite sum, a payment date and a signature.
What the note has to state
A compliant note states the principal, the annual interest rate and how it accrues, the payment dates and amounts, the final payment, and the authority of each signer. It names the events of default, the cure period, the seller's right to accelerate, and the governing law.
Promissory note required terms
Term
- Principal
- Amount financed
- Interest
- Annual rate, accrual
- Security
- Collateral schedule, lien
- Default
- Triggers, cure, remedies
What it must say
- Principal
- Buyer, seller, IRS
- Interest
- State usury regulator
- Security
- UCC Article 9
- Default
- A court, if enforced
Who reads it
- Principal
- Interest
- Security
- Default
Leave the rate blank or bury it, and the IRS can treat part of the principal as interest under the applicable federal rate. Publication 537 explains how a seller reports an installment sale.
| Term | What it must say | Who reads it |
|---|---|---|
| Principal | Amount financed and application of payments | Buyer, seller, IRS |
| Interest | Annual rate, accrual basis, default rate | State usury regulator |
| Security | Collateral schedule and lien position | UCC Article 9 |
| Default | Triggers, cure period, remedies | A court, if enforced |
Records a seller has to keep
Keep the executed note, the security agreement with its collateral schedule, the file-stamped financing statement and the state's filing acknowledgment. Keep the amortization schedule, a ledger showing how each payment was applied, and the buyer's annual statements. Diary the five-year anniversary of the UCC-1. The filing lapses unless a continuation is filed within the six months before it expires.
Seller's note file
- Executed note and security agreement
- File-stamped UCC-1 and acknowledgment
- Continuation deadline on a watched calendar
- Payment ledger showing each receipt
The buyer's bank decides whether the seller may hold a lien at all. Most senior facilities carry a negative pledge, so the acquisition financing file will show whether a seller lien is permitted, subordinated or barred.
What happens when the terms or filings fail
A financing statement that lapses leaves the security interest unperfected. The seller becomes a general unsecured creditor, behind the bank, behind a judgment creditor that filed first, and behind a bankruptcy trustee. A rate above the state ceiling can void the interest, and in a few states it costs the seller more than that.
Perfection is a filing, not an intention. The seller either holds a recorded lien or holds a promise.
The buyer's side sees the same defect. A purchaser who inherits a defective lien spends the first year arguing about it, which is why businesses for sale requirements begin with the documents the seller must produce.
Where the rules differ by place
The usury ceiling follows the transaction, not the letterhead. A note made and performed in one state usually takes that state's limit. A choice-of-law clause pointing to a friendlier state can fail.
UCC filing location is mechanical. File where the debtor is organized: the state of incorporation for a corporation, the state of formation for a limited liability company, and the principal residence for an individual. A lien on real property is a mortgage recorded with the county.
Sellers who assemble the file before the business goes to market fix these problems while the buyer still needs something from them. A seller preparation comparison sets out what that preparation covers.
Example: a lien that lapsed at the five-year mark
A seller carries a note on the sale of a company's assets and takes a security interest in equipment and inventory. The UCC-1 goes to the state where the business operates, not the state where the buyer's LLC was formed, so the filing never attaches.
How the lien lapsed
- ClosingUCC-1 filed in wrong state
- Five years onContinuation deadline passes
- After lapseSeller holds unsecured claim
Five years on, the continuation deadline passes unremarked. What the seller holds is an unsecured claim. A valuation methods review will value that claim below face value.
Common questions
Does a seller have to file anything to hold collateral?
Yes. The security agreement creates the interest; the UCC-1 filed where the debtor is organized perfects it. Without that filing the seller is an unsecured creditor.
Can the seller charge any rate the buyer accepts?
No. State usury law caps the rate, and the cap usually comes from the state where the loan is made and performed.
What happens if the buyer sells the business?
An assignment or due-on-sale clause decides whether the note survives. Without one, the seller may end up chasing an entity that no longer holds the collateral.
Who reports the interest on the note?
The seller reports interest as ordinary income and the gain under the installment method. A buyer may deduct that interest as business debt.